Check eligibility
Choose the taxpayer type and enter taxable income before the QBI deduction.
Preview free. Use HALLOWEEN50 at checkout and save 50%.
Forms purchased on this site only. Excludes pay stubs and the separate Offer Letter tool. Ends Oct 31, 2026 at 11:59 pm Eastern.
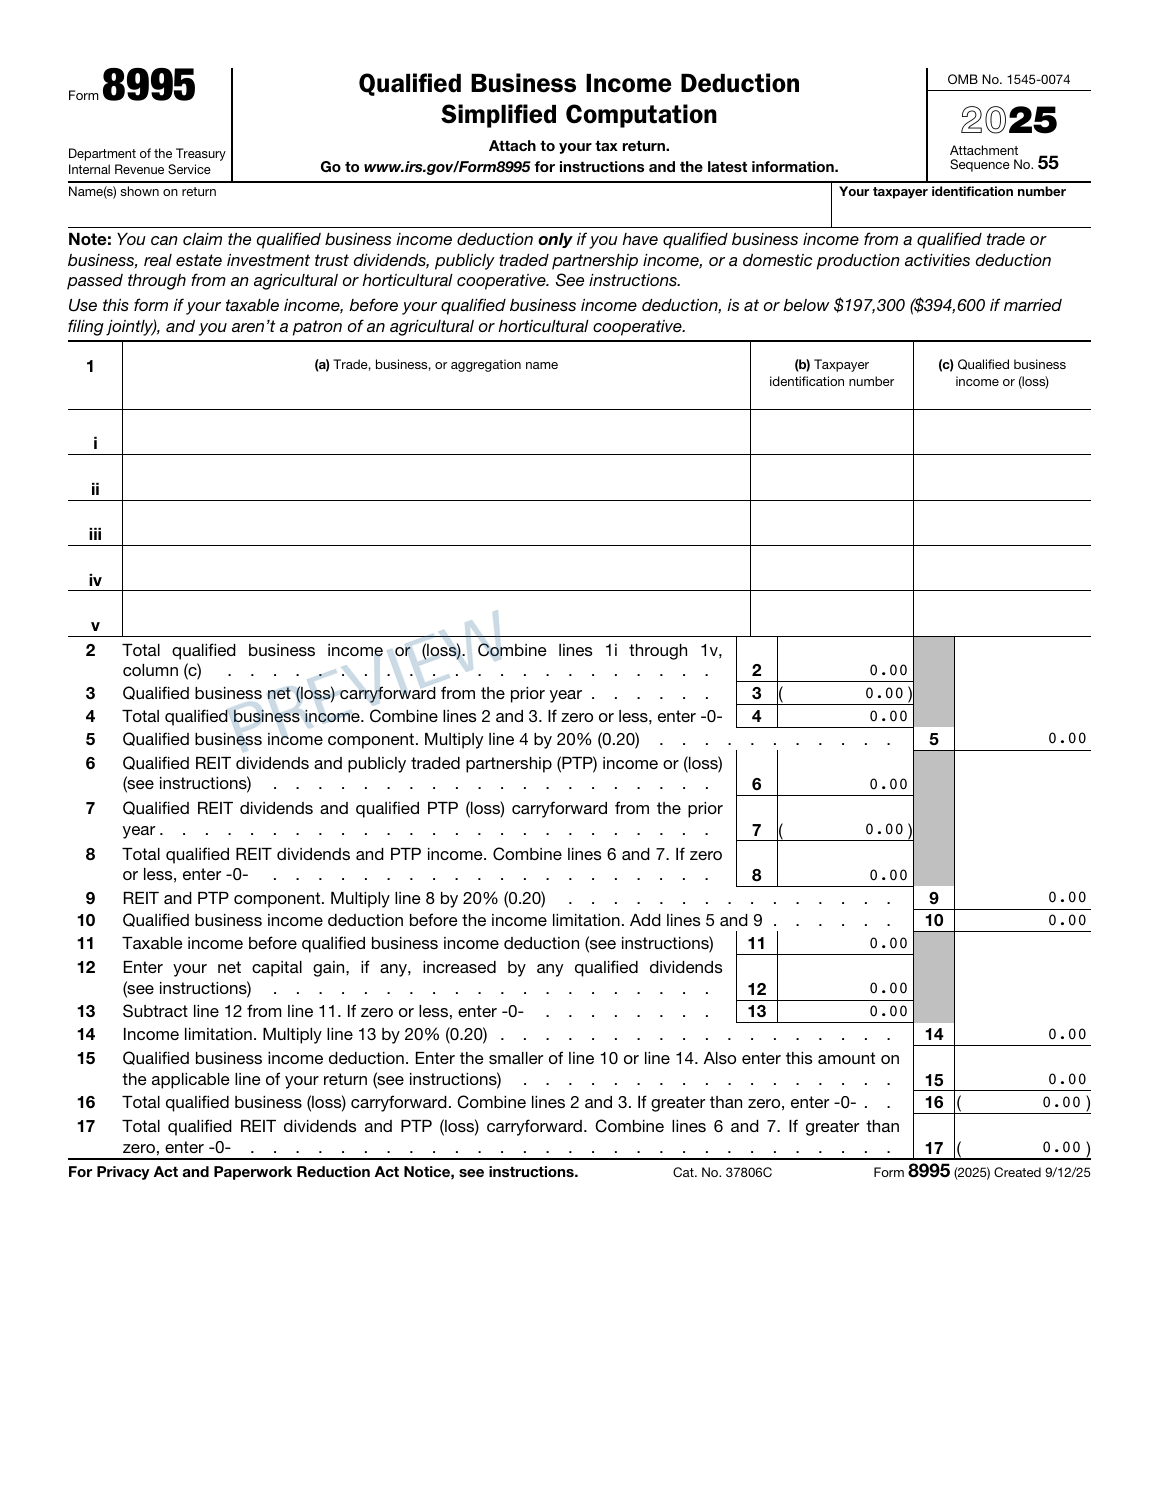
Organize qualified income and loss records, apply the simplified computation and review the complete original IRS form.
Complete PDF · Preview free
Pay when ready to download
Final 2025 IRS original. The final 2026 edition will be added when available.
Choose the taxpayer type and enter taxable income before the QBI deduction.
Enter business QBI, any REIT / PTP amounts, allowed prior losses and net capital gain / qualified dividends.
Check the deduction limits, loss carryforwards and complete PDF before checkout.
The original page, field layout and white margins stay intact. Entries beyond the first five businesses appear on an included additional-business statement.
The Form 8995 preparation guide explains business components, carryforwards and deduction-limit checks to review before entering your amounts.
Use actual allowed QBI and related amounts from required source worksheets. This prepares Form 8995; it does not calculate business eligibility, all underlying income / loss limitations, trust allocations or a complete tax return. Aggregation and rental safe-harbor statements are separate.
For 2025, taxable income before QBI must be at or below $197,300, or $394,600 if married filing jointly. Specified agricultural / horticultural cooperative patrons use Form 8995-A. Partnerships and S corporations pass information to owners rather than claim this deduction themselves. Review the current IRS instructions ↗.
No. Enter actual qualified net amounts after attributable deductions and applicable limitations. Ordinary employee wages, capital gains and C-corporation income are generally excluded. REIT / PTP amounts use a separate component.
The builder supports up to 20 entries. The first five appear on the original page, the remainder on a supporting statement. All entries are included once in Line 2.
Use a minus sign for current qualified business or PTP losses. Enter positive magnitudes for prior qualified losses on Lines 3 and 7; they are subtracted once. Amounts still suspended by other tax rules require separate tracking.
Enter the aggregation group name and leave its taxpayer-number column blank. Prepare and attach Schedule B (Form 8995-A) or a similar aggregation schedule, including required pass-through disclosures. A rental safe-harbor enterprise also needs its separate required statement.
Eligible estates / trusts can prepare the simplified computation for their own qualifying portion. Exclude amounts allocated to beneficiaries. An ESBT must compute S and non-S portions separately; the optional S-portion choice adds the required ESBT top-margin marker.
No. Download and attach the form to your separately prepared return with required worksheets / statements. IRS filing and tax payments are not included.
$9.99 USD covers one complete original Form 8995, an additional-business sheet when applicable and private completed-order access.
One Form 8995. $9.99 USD.